Turnkey Property: What the Premium Buys and What It Costs
Discover the benefits of a turnkey property investment - what you get and what it costs. Take the first step towards financial freedom today!
A turnkey property is a rental sold in rent-ready condition, often with a tenant and property management already in place. Instead of buying a distressed house, managing renovations, and finding the first tenant, the investor acquires an operating rental.
That convenience is usually reflected in the purchase price.
Turnkey providers typically build acquisition costs, renovation work, lease-up, operating setup, and their own profit margin into what the buyer pays. The useful question is therefore not simply whether turnkey properties cost more. It is whether the premium is reasonable relative to the work, risk, time, and local execution the investor avoids.
Once that difference is priced explicitly, turnkey becomes easier to compare with the alternatives.
What Does Turnkey Rental Mean for Property?
In real estate, turnkey generally describes a property that can begin operating as a rental without the buyer first completing a substantial renovation or lease-up.
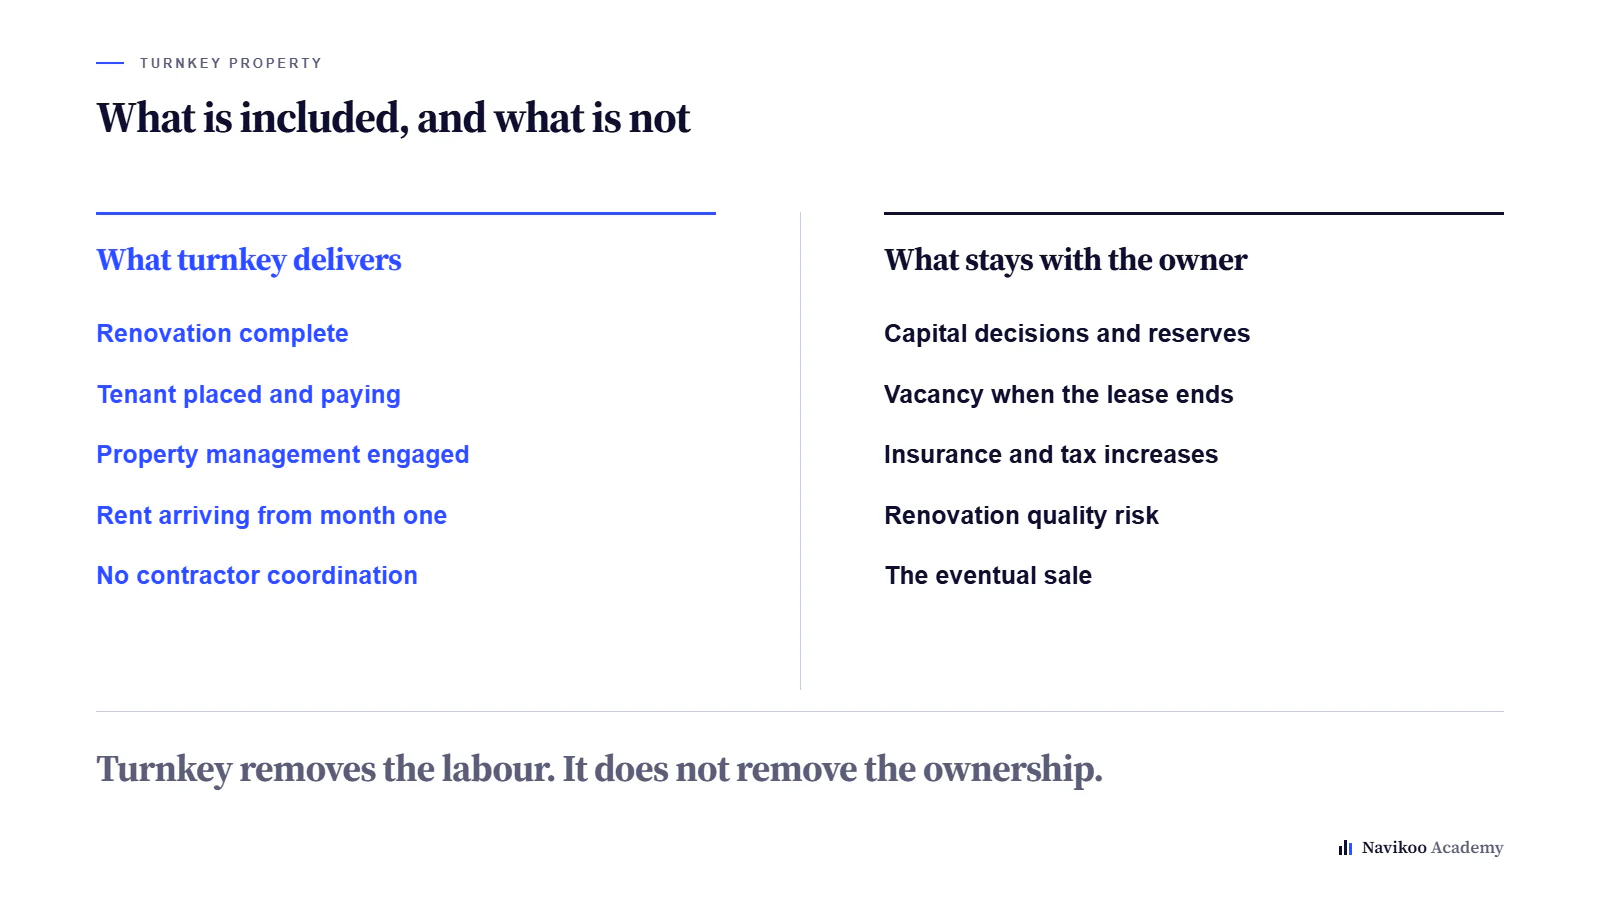
The exact package varies by provider. A turnkey property may include:
completed renovations
an existing tenant
a current lease
property management already arranged
maintenance management
financial reporting systems
Single-family rentals are common in the turnkey market, although condos and small multifamily properties can also be sold through the same model.
The service solves a practical problem. Acquisition, renovation, leasing, and management all require local knowledge. An investor living hundreds or thousands of miles away may not have contractors, leasing agents, inspectors, or property managers they already trust.
A turnkey provider assembles much of that infrastructure before the investor enters the market.
What Turnkey Property Does Not Mean
Turnkey describes readiness, not quality.
A property can look finished while still containing older mechanical systems, deferred exterior work, or materials selected primarily to photograph well for resale.
The label also does not make real estate ownership completely passive.
Even with professional management, the owner remains responsible for decisions involving:
major repairs
insurance
property taxes
capital improvements
vacancies
manager performance
refinancing
eventual sale
Turnkey investments can outsource much of the day-to-day work. It does not transfer the investment risk to someone else.
How Turnkey Real Estate Actually Works
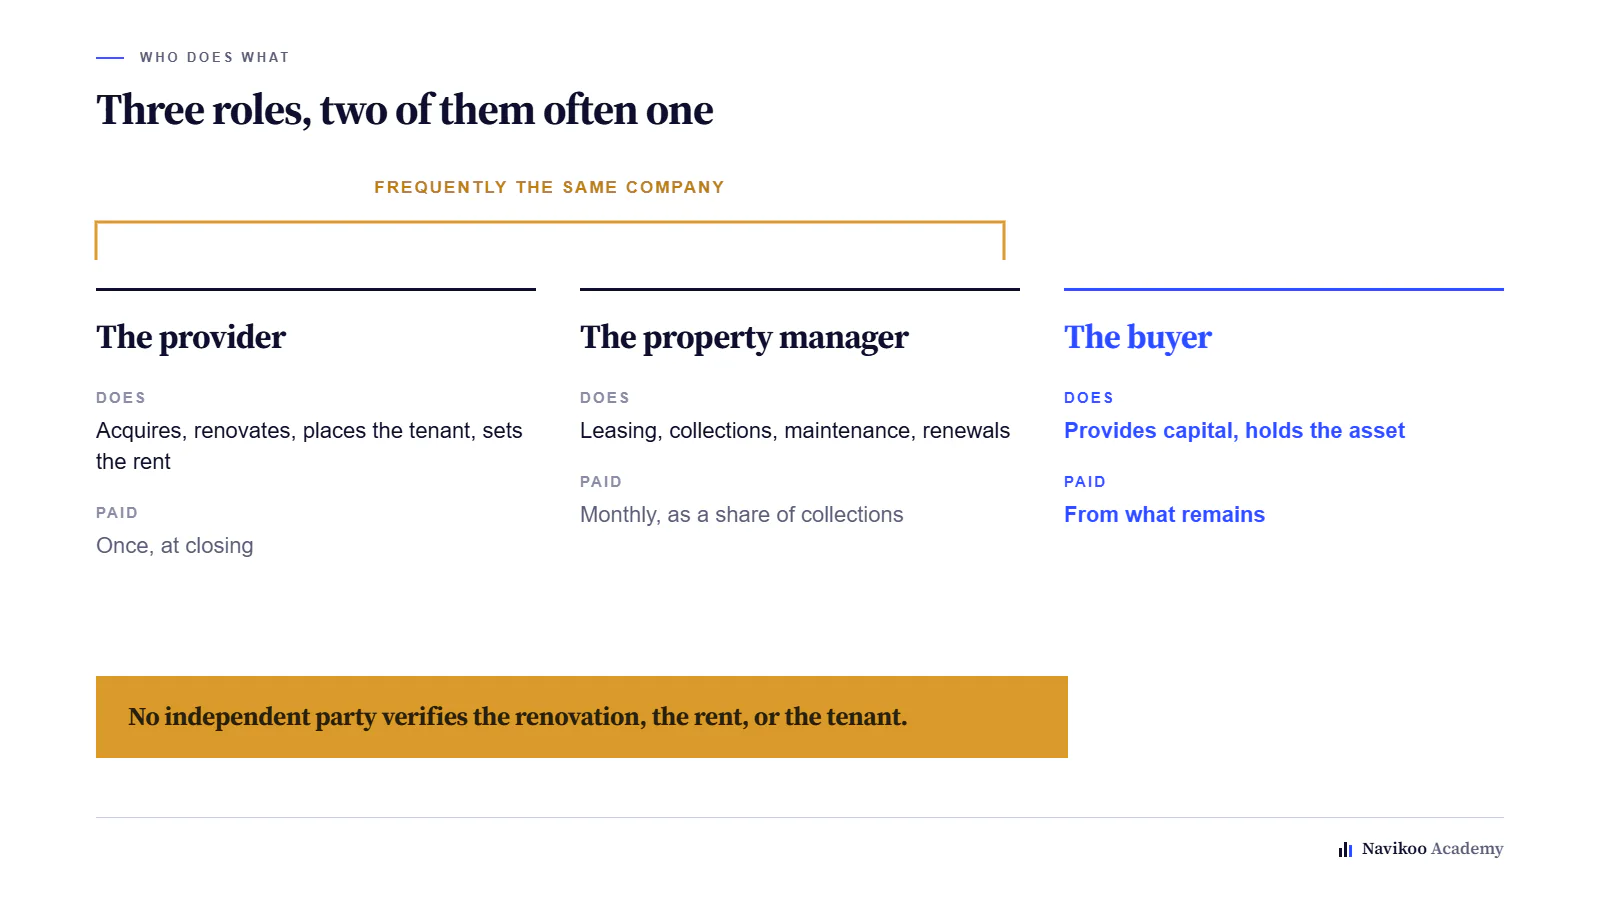
A typical turnkey transaction involves a provider, a property manager, and the investor.
The Provider
A turnkey provider acquires a property, renovates it, prepares it for rental use, places a tenant in some cases, and sells the finished asset.
The provider generally earns a development or resale margin through that process.
That margin is not inherently a problem. Renovation management, sourcing properties, carrying the asset during construction, leasing, and building local operating systems all have economic value.
The buyer's job is to determine how much they are paying for those services.
The Property Manager
The property manager handles the operating side after acquisition.
Typical tasks include:
rent collection
tenant communication
maintenance coordination
lease renewals
inspections
turnover
reporting
Management is what allows an investor to own a property in another market without operating it personally.
Fees vary by company and market, so the management agreement deserves the same attention as the purchase contract.
Where the Two Overlap
Some turnkey providers operate their own property management business or maintain a closely affiliated manager.
That structure can create efficiencies because the same organization already knows the property, tenant, and renovation history.
It also means several important assumptions may originate from the same source.
The provider may have:
selected the property
completed the renovation
estimated market rent
selected the tenant
prepared the pro forma
recommended the property manager
That does not make the arrangement improper. It makes independent verification more valuable.
A buyer can separately verify the two assumptions that matter most: property condition and sustainable rent.
Pricing the Turnkey Premium
The most useful comparison is between the turnkey purchase price and what a similar finished rental might have cost the investor to assemble independently.
The estimate does not need to be perfect.
Its purpose is to make the convenience premium visible.
The Same Asset, Two Ways
Consider a hypothetical single-family rental leased at $1,750 per month.
These figures are illustrative teaching assumptions rather than current market data.
Item | Annual Amount |
|---|---|
Gross rental income ($1,750 × 12) | $21,000 |
Vacancy at 6% | −$1,260 |
Effective gross income | $19,740 |
Property management at 9% | −$1,780 |
Property taxes | −$2,400 |
Insurance | −$1,300 |
Maintenance | −$1,500 |
Reserves | −$1,100 |
Administrative | −$400 |
Total operating expenses | −$8,480 |
Net operating income | $11,260 |
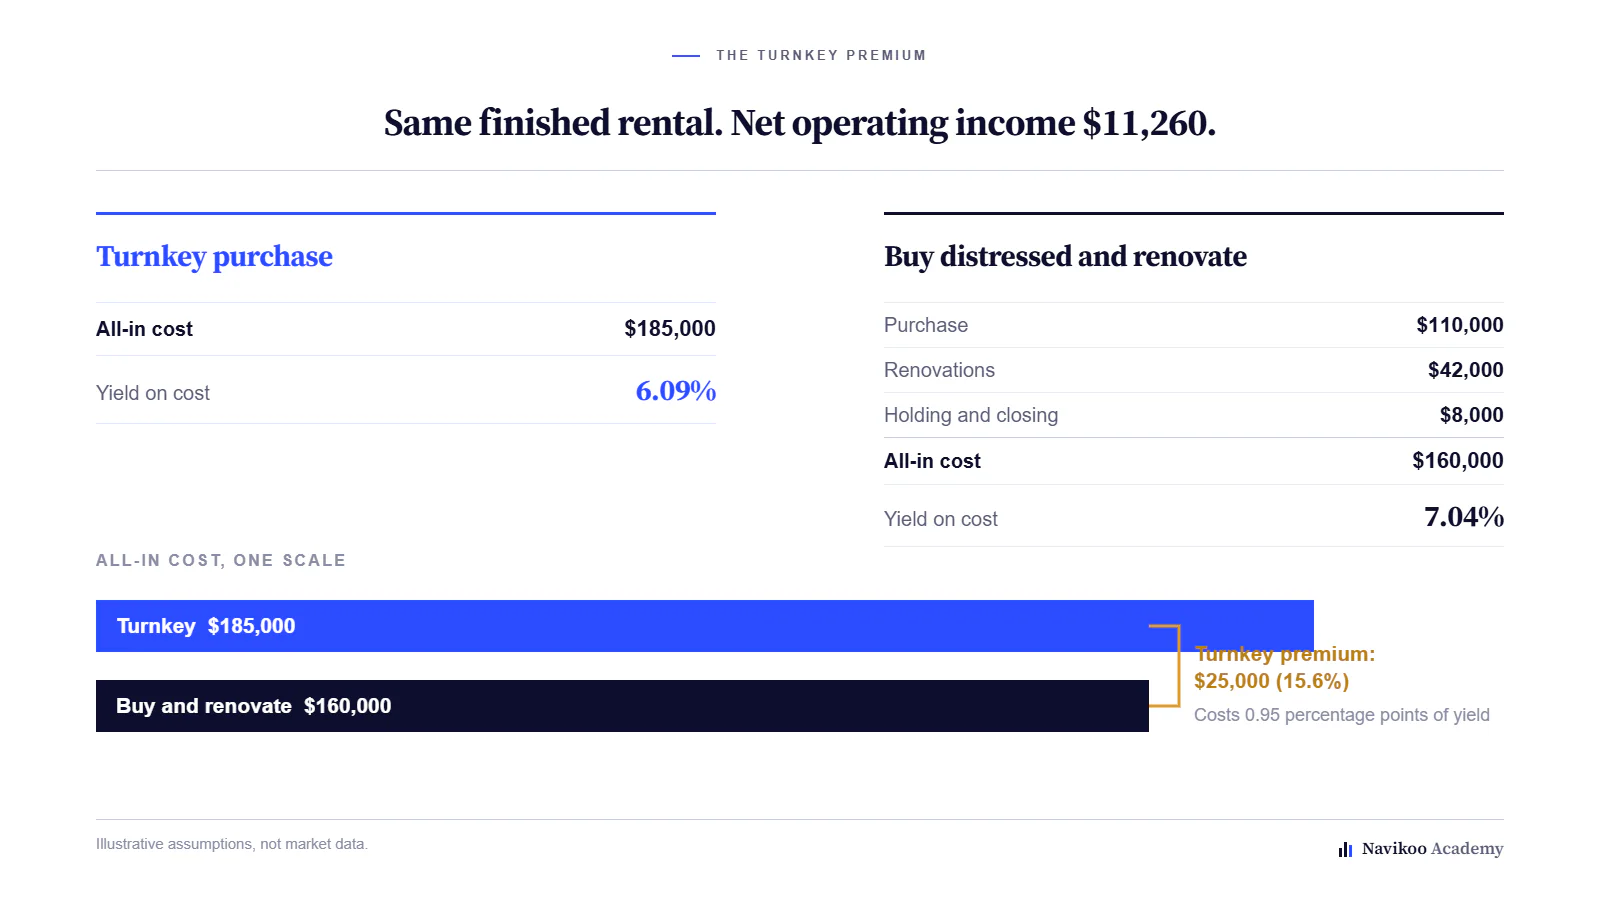
Now compare two hypothetical ways of acquiring the same finished rental.
Route | All-in Cost | Yield on Cost |
|---|---|---|
Turnkey purchase | $185,000 | 6.09% |
Independent acquisition + rehab | $160,000 | 7.04% |
The independent route assumes:
$110,000 purchase
$42,000 renovation
$8,000 closing and holding costs
The difference is $25,000, or approximately 15.6% above the independent all-in cost.
The property's NOI is identical in both examples.
What changed is the amount of capital required to own the finished asset.
That reduces the unleveraged yield from approximately 7.04% to 6.09%.
The $25,000 premium covers more than convenience. It pays for finding the property, managing the renovation, carrying the property during the process, finding a tenant, coordinating everything locally, and the provider’s profit.
What $25,000 Buys Per Year
One way to understand the scale of the premium is to spread it across an assumed holding period.
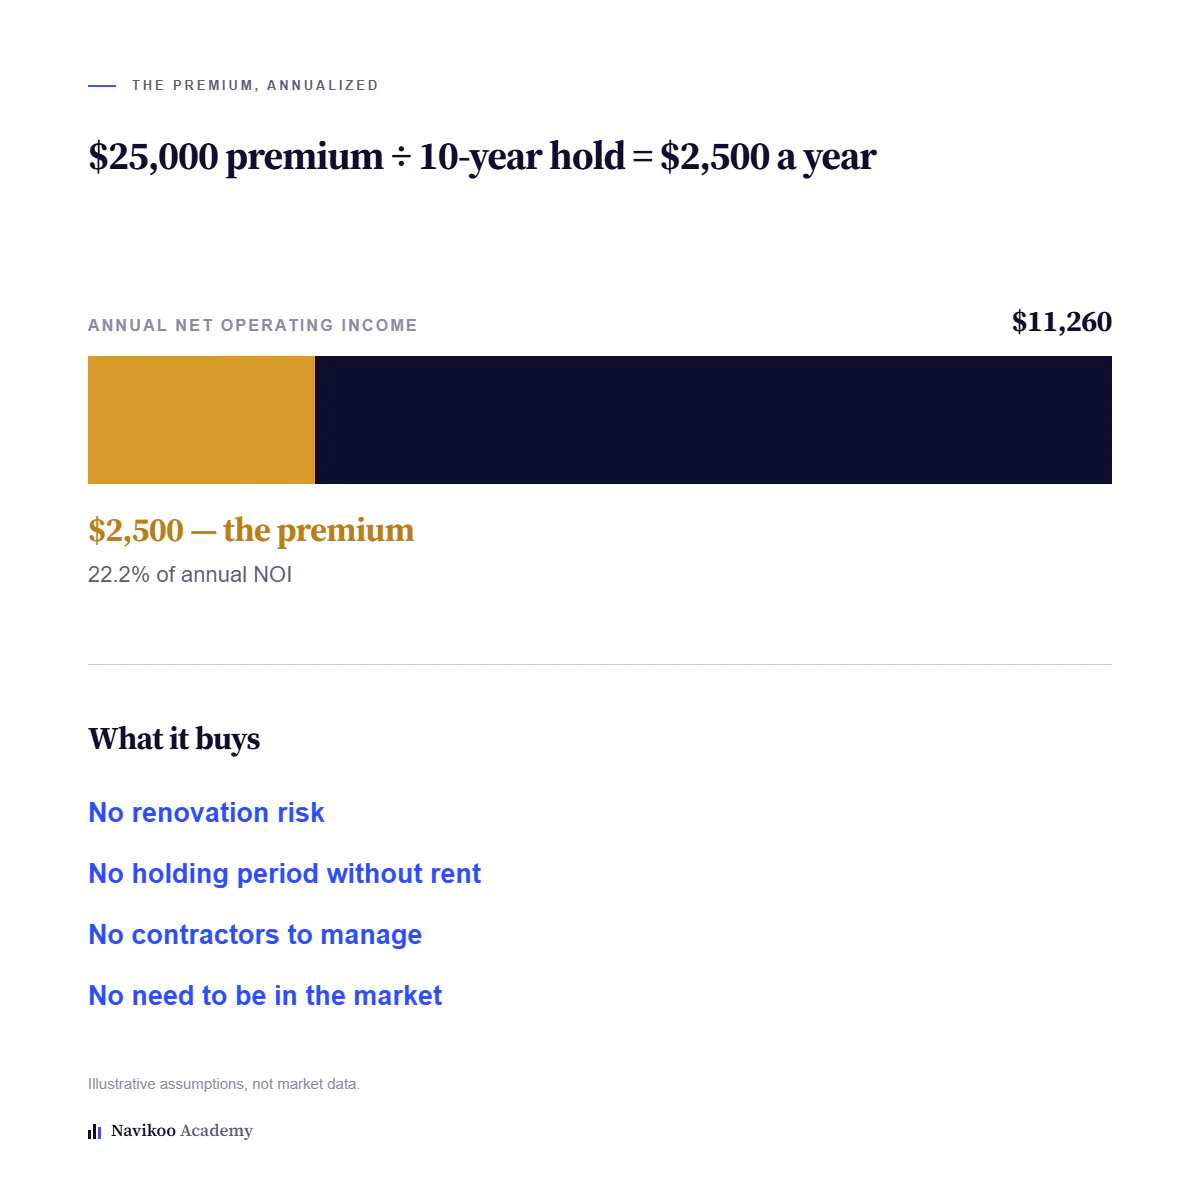
Over a hypothetical ten-year hold:
$25,000 ÷ 10 = $2,500 per year
That figure equals roughly:
$2,500 ÷ $11,260 = 22.2% of one year's NOI
This does not mean the investor pays an additional $2,500 operating expense every year. The premium is paid upfront as part of the acquisition basis, and this simplified comparison also ignores the time value of money.
It does show that the convenience being purchased is economically meaningful.
In exchange, the investor may avoid:
renovation execution risk
a vacant construction period
contractor coordination
local leasing work
repeated travel
building a management network from scratch
The value of those services depends heavily on the buyer.
An investor with reliable local contractors and renovation experience may view $25,000 as expensive.
Someone with a demanding career, no local presence, and little interest in managing construction may reasonably value the same package much more highly.
The important step is identifying the premium before deciding whether it is worth paying.
The Tenant in Place - The Landlord Peace
An existing tenant can eliminate the initial lease-up period and create rental income immediately after closing.
That is valuable only if the rent is sustainable.
The current lease should therefore be treated as a piece of evidence, not proof of long-term market rent.
When the Lease Resets
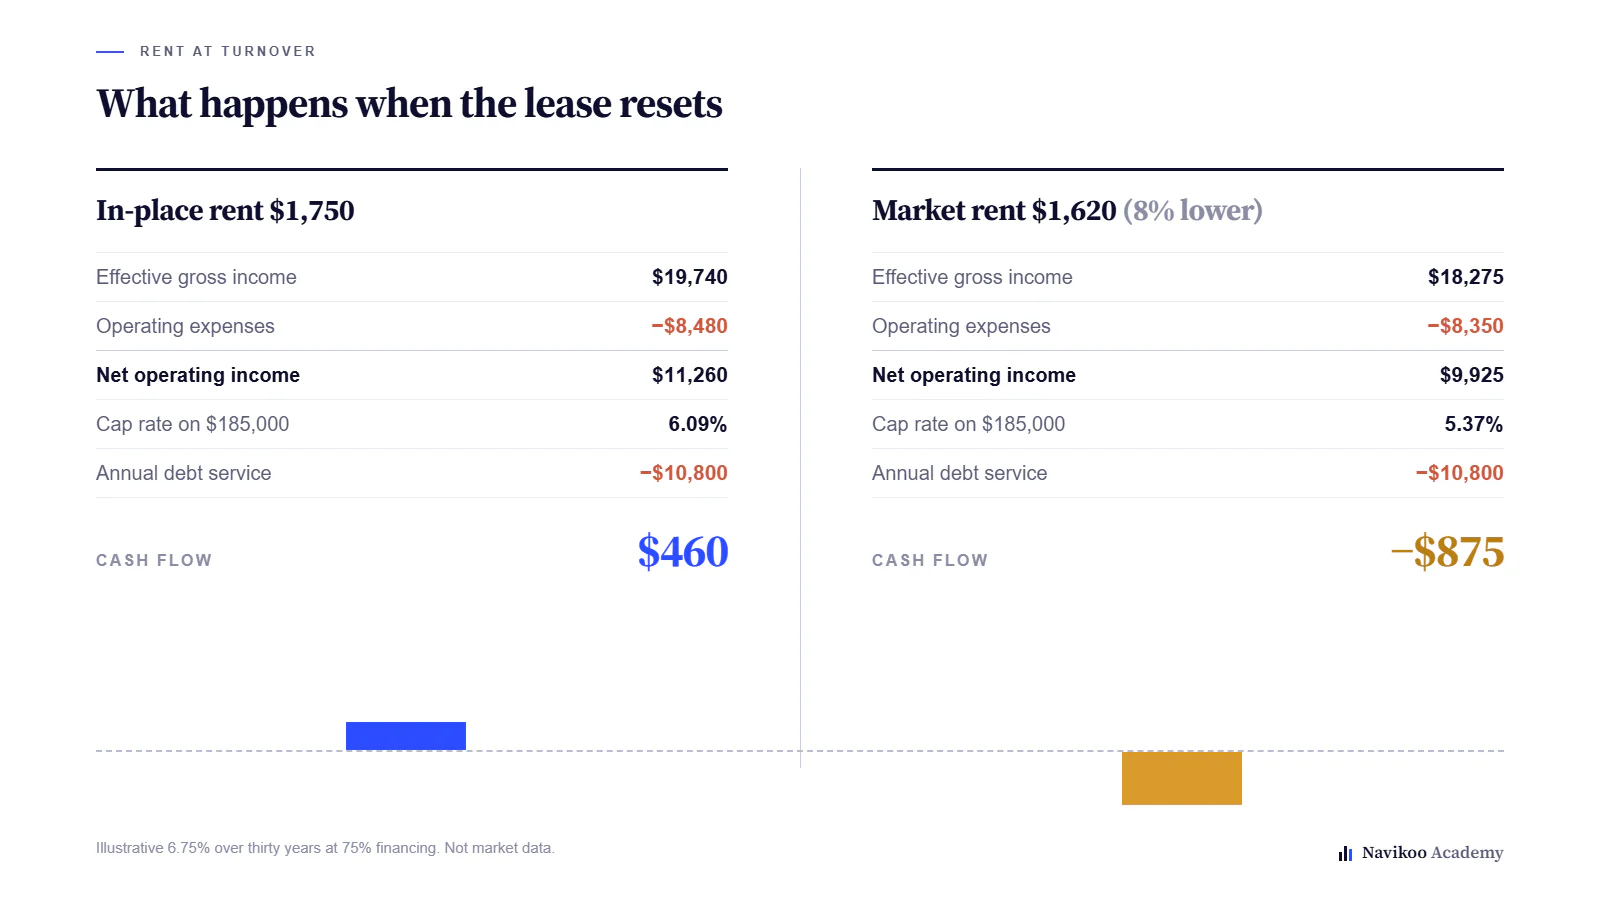
Suppose the hypothetical tenant pays $1,750 per month, but comparable rentals support closer to $1,620.
The in-place rent is roughly 8% above the comparable market level.
Item | In-Place Rent: $1,750 | Market Rent: $1,620 |
|---|---|---|
Effective gross income | $19,740 | $18,275 |
Operating expenses | −$8,480 | −$8,350 |
Net operating income | $11,260 | $9,925 |
Cap rate on $185,000 | 6.09% | 5.37% |
NOI declines roughly 11.9% even though rent falls by about 8%.
The reason is that many expenses change very little when revenue declines.
Now add financing.
Assume 75% leverage on the $185,000 purchase:
Loan amount = $138,750
At an illustrative 6.75% rate with 30-year amortization, annual principal and interest are approximately $10,800.
At the in-place rent:
$11,260 − $10,800 ≈ $460 annual cash flow
At the lower market rent:
$9,925 − $10,800 ≈ −$875
A thinly cash-flowing property becomes a negative-cash-flow property when the lease resets.
That is why an occupied turnkey rental should still be underwritten using independently verified market rent.
What to Check in the Financials
Start with actual payment history.
A signed lease shows what the tenant agreed to pay. Payment records show what they actually paid and whether they paid it consistently.
Ask for:
the current lease
twelve months of payment history when available
security deposit documentation
delinquency history
renewal history
any concessions or credits
Then compare the current rent with competing properties.
A third-party rent analysis, local property manager, or several genuinely comparable active listings can help establish whether the current lease reflects the market.
The goal is not to prove the provider wrong.
It is to determine whether the income supporting the purchase price is likely to survive the next renewal.
What Are the Cons of a Turnkey Investment?
Several disadvantages come directly from the structure of the model.
The Margin Is Earned on Day One
Most of the provider's development or resale margin is realized when the property is sold.
The buyer then bears the long-term investment performance.
The provider may still have economic incentives after closing through property-management fees, repeat business, warranties, or reputation. Those incentives can be meaningful, but they are different from owning equity alongside the investor.
Buyers should therefore evaluate the transaction based on their own underwriting rather than assuming the provider's interests remain identical after closing.
Distance
Access to opportunities in other markets is one of the strongest reasons to use a turnkey provider.
Distance is also one of its risks.
An investor who never visits the market may rely heavily on:
listing photographs
provider descriptions
neighborhood statistics
manager reports
Those sources can all be useful without replacing independent local verification.
A third-party inspection, local rent analysis, street-level research, and conversations with third-party professionals with the seller can fill much of that gap.
Renovation Quality
A finished property can look excellent while containing systems approaching the end of their useful lives.
Cosmetic work is easy to photograph.
Electrical panels, plumbing, roofing details, drainage, HVAC condition, sewer lines, and workmanship behind finished surfaces are less visible.
An independent inspection commissioned by the buyer remains worthwhile even when the property has recently been renovated.
The relevant question is not simply:
“Was it renovated?”
It is:
“What was replaced, what was repaired, and what was left untouched?”
Limited Upside
Turnkey buyers generally acquire an already stabilized property.
That means much of the value created through:
buying distressed
renovating
leasing
stabilizing operations
has already been captured before the buyer enters.
Future returns may therefore depend more heavily on:
rental income
rent growth
mortgage amortization
appreciation
long-term operating performance
An investor whose strategy depends on creating substantial forced appreciation may prefer a value-add acquisition.
Pros and Cons of Turnkey Properties
The benefits of turnkey properties cluster around speed, convenience, and geographic access. The trade-offs center on price, control, and reliance on third parties.
Pros | Cons |
|---|---|
Potential rental income immediately after closing | Purchase price may include a meaningful provider premium |
Renovation already completed | Buyer must independently verify renovation quality |
Easier access to distant markets | Distance reduces direct oversight |
Management infrastructure may already exist | Provider and manager may be affiliated |
Repeatable acquisition process | Less opportunity to create value through renovation |
The comparison depends heavily on what the investor could do instead.
Someone capable of sourcing, renovating, leasing, and managing a property locally should compare turnkey against that independent route.
Someone who would otherwise remain entirely outside the market has a different alternative.
For that investor, the comparison may be:
turnkey ownership versus not owning the property at all.
The appropriate benchmark is the opportunity the buyer could actually execute.
Financing a Turnkey Purchase
Many turnkey rentals can be financed using standard investment-property loan products because they are already renovated and rent-ready, subject to lender underwriting and property qualifications.
That can be easier than financing a distressed property requiring substantial work.
Investors should still expect terms to differ from owner-occupied mortgages.
Depending on the lender and loan program, differences can include:
larger down payments
higher interest rates
reserve requirements
stricter debt-to-income criteria
different appraisal standards
Terms vary enough that financing assumptions should come from an actual lender quote rather than a general rule.
The finished condition of a turnkey property can also shorten the acquisition timeline because there is no renovation period before stabilization.
Speed is useful, but it should not replace due diligence.
A ready-to-close property deserves the same inspection, rent verification, title review, insurance review, and underwriting as any other rental.
Are Turnkey Properties Worth It?
The answer depends on the problem the investor is trying to solve.
Where Turnkey Genuinely Fits for Investors
Turnkey can make sense for an investor with:
capital available
limited time
strong income from other sources
little interest in managing construction
a home market where rental economics are unattractive
a desire to invest in another city
In that situation, the provider is solving a genuine execution problem.
Buying a rental property in another state independently requires building relationships with:
agents
contractors
inspectors
leasing professionals
property managers
A good turnkey operation compresses that learning curve.
The model can also appeal to first-time investors who want to learn the basics of owning and managing a rental property without taking on a renovation at the same time.
The premium is partly payment for removing variables from the first acquisition.
Where It Does Not
Turnkey becomes less compelling when the investor already has the skills, network, and time required to create a comparable property for substantially less.
It is also less attractive when the investor's actual objective is simply passive exposure to real estate rather than direct property ownership.
That leads to a different comparison.
Turnkey Properties Against a REIT
An investor primarily seeking passive real estate exposure should compare direct ownership with publicly traded real estate investments as well.
A publicly traded real estate investment trust provides real estate exposure without directly owning or managing a rental property.
The two approaches offer very different forms of ownership.
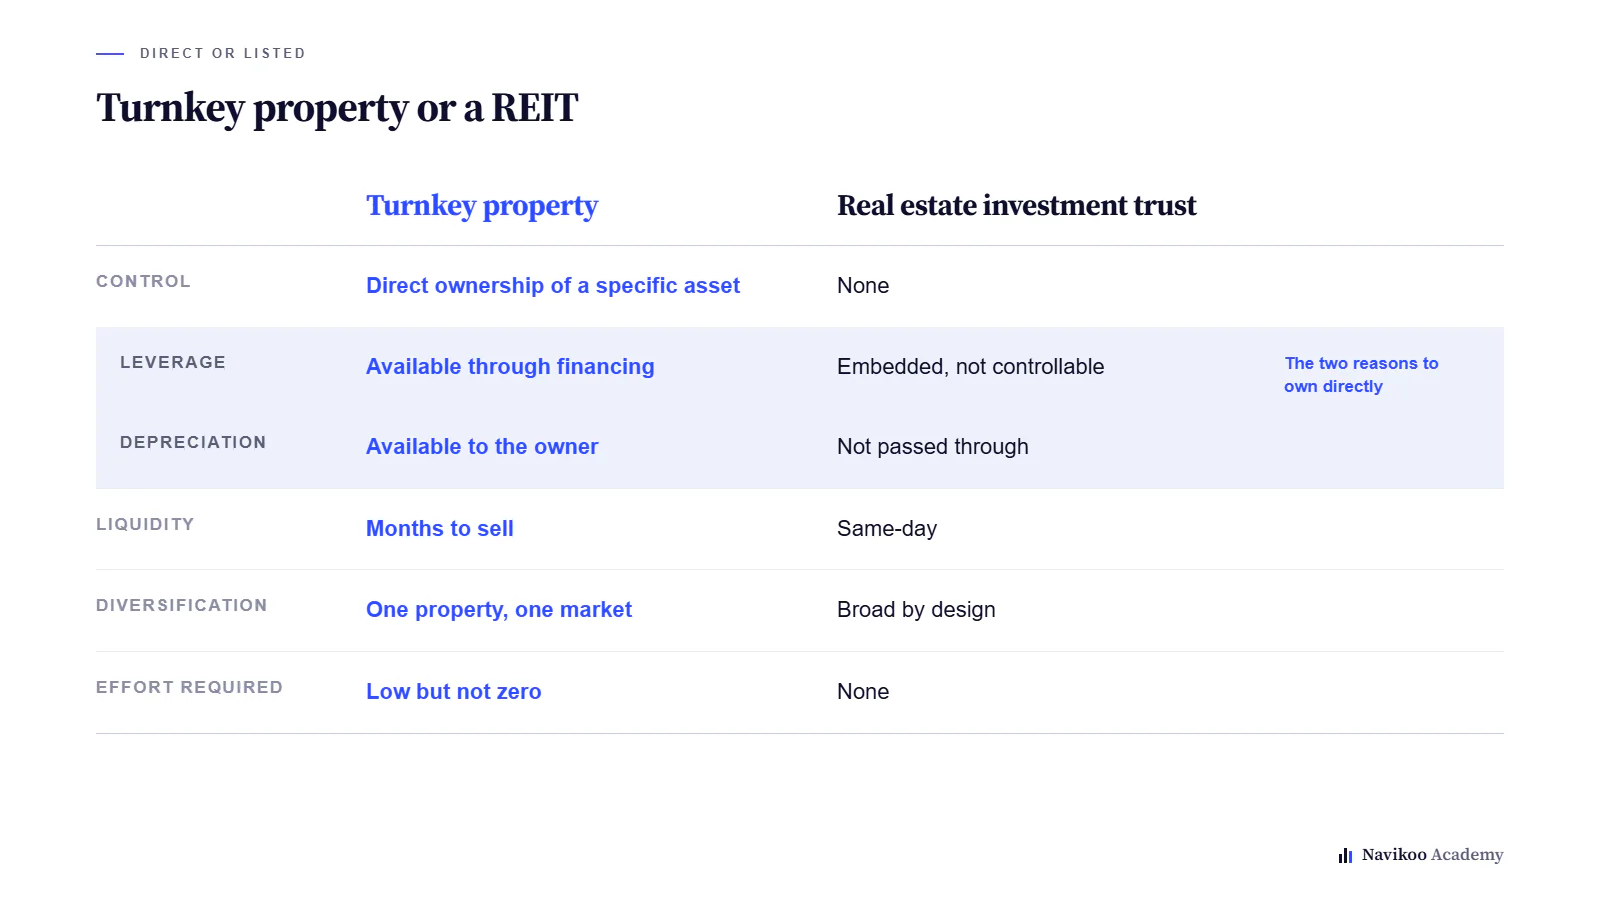
Factor | Turnkey Property | Publicly Traded REIT |
|---|---|---|
Control | Direct ownership of a specific asset | Investor does not control individual properties |
Leverage | Investor chooses property-level financing | Leverage exists at the REIT level and is not controlled by the shareholder |
Tax treatment | Direct ownership has property-level income, deductions, and depreciation considerations | Investor receives the tax treatment associated with REIT distributions and securities ownership |
Liquidity | Sale may take weeks or months | Shares are generally tradable during market hours |
Diversification | Concentrated in one property and market | Often diversified across many properties |
Effort | Low with good management, but not zero | Very little direct operating involvement |
Tax consequences vary by investor, property structure, account type, and REIT.
Direct ownership should therefore not be compared with REIT investing using a simplified assumption that one produces a superior tax outcome.
The more useful differences are:
control
leverage
concentration
liquidity
workload
Direct ownership allows an investor to choose the property, debt structure, manager, and eventual disposition.
A publicly traded REIT provides diversification and liquidity with far less operating involvement.
Turnkey Properties and Your Investment Goals
Turnkey property is often marketed around passive income and financial freedom.
The arithmetic deserves more attention than the slogan.
Suppose a property produces only a few hundred dollars per month after expenses and financing.
That income is useful, but replacing a salary would require:
multiple properties
substantially higher cash flow per property
lower debt over time
rent growth
some combination of those factors
Turnkey is therefore better understood as a repeatable ownership model than as a shortcut to financial independence.
For someone seeking to build a portfolio of rentals across one or more distant markets without becoming a full-time landlord, that repeatability can be valuable.
For someone expecting one or two properties to replace employment income quickly, the economics may not support the expectation.
How to Vet a Turnkey Company
The quality of the provider affects nearly every part of the investment because the provider may influence the acquisition, renovation, tenant placement, and management structure.
Due diligence should therefore extend beyond the individual property.
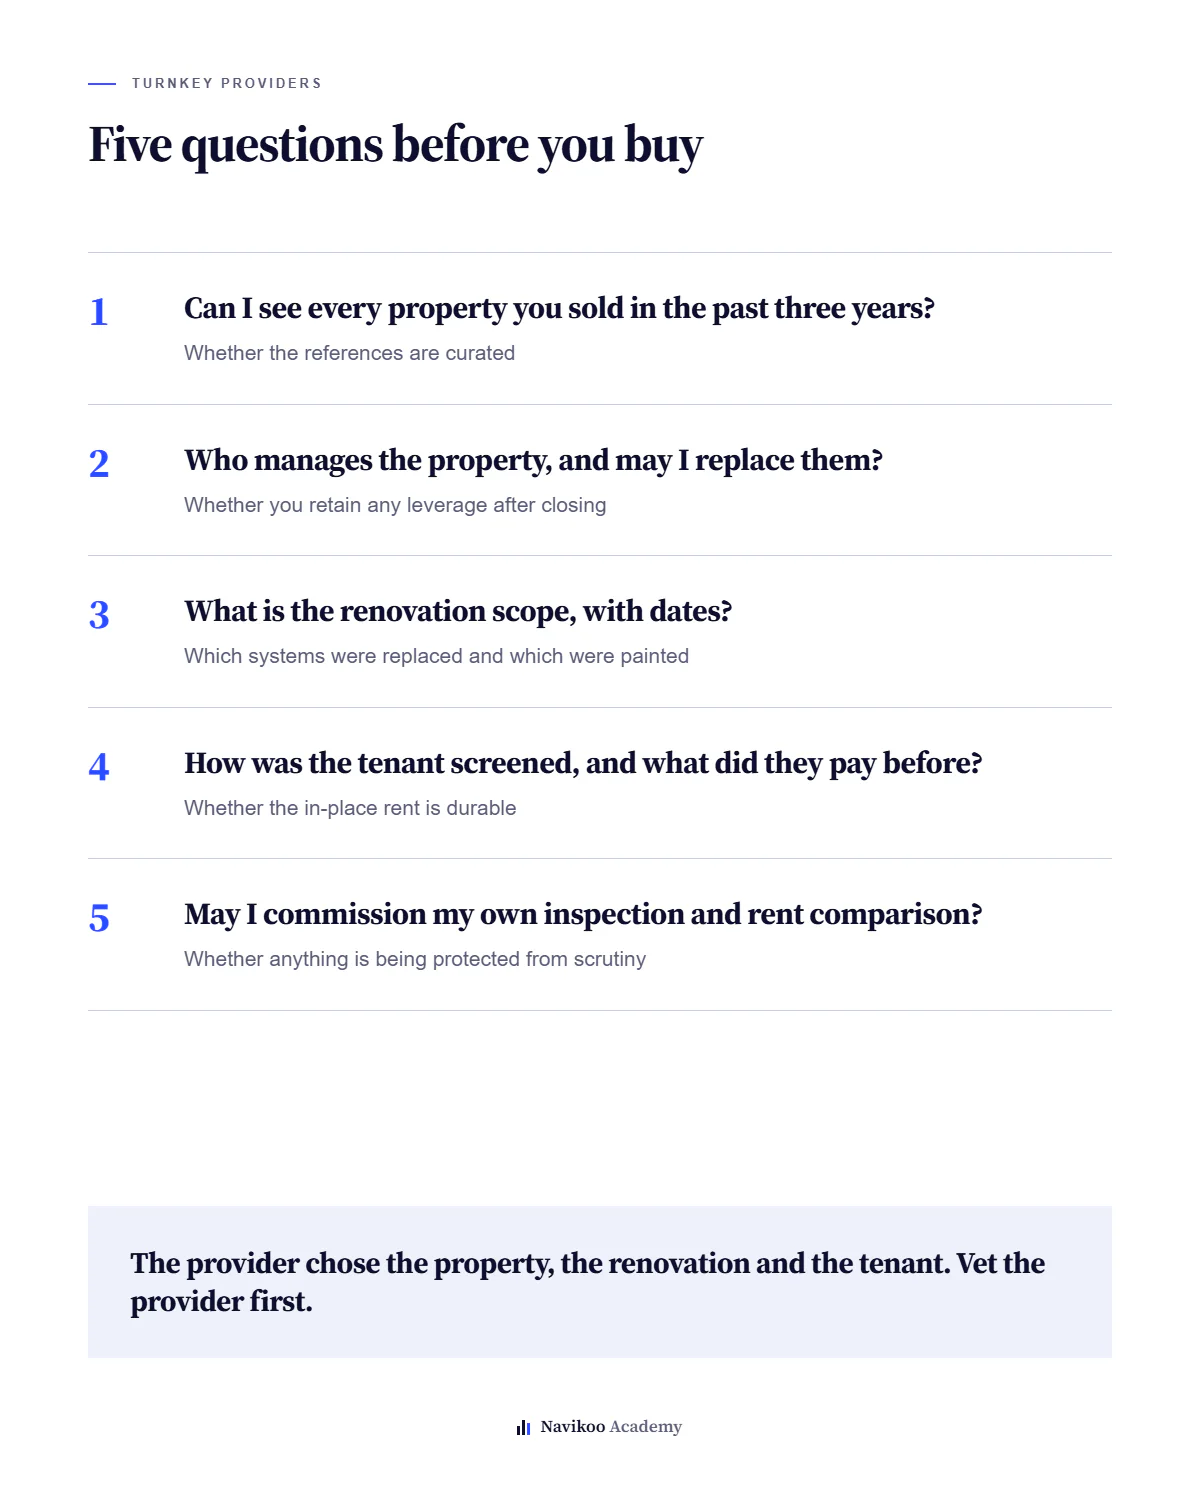
Ask for information about previously sold properties, not just the units currently available.
If possible, speak with previous buyers who have owned properties long enough to experience:
maintenance
tenant turnover
rent renewals
manager communication
unexpected capital expenses
Ask whether property management is optional and what happens if the investor wants to replace the manager later.
Review the renovation scope rather than relying only on listing photographs.
The scope should clarify:
what was replaced
what was repaired
approximate completion dates
which major systems remain older
Review the tenant information as well.
Understand:
when the lease began
the rent amount
payment history
screening process
lease expiration
whether concessions were offered
Finally, obtain independent verification of the two assumptions carrying the most weight:
condition and rent.
An independent inspection addresses the first.
An independent rental analysis addresses the second.
Neither eliminates investment risk. Together they reduce the buyer's dependence on information supplied by the party selling the property.
Key Takeaways Before You Buy
Start by estimating what a similar finished rental might cost to assemble independently.
The difference between that figure and the turnkey purchase price provides a rough estimate of the premium being paid for execution, time, convenience, and provider margin.
Then verify the rent and market rent (you can use our Rent Estimator for free).
An occupied property is valuable because the lease-up period has already been completed, but the current lease should still be compared with realistic market rents.
Verify the condition separately.
A recent renovation does not reveal which systems were replaced, repaired, or left alone.
Review the management relationship as carefully as the property itself, particularly when the manager is affiliated with the provider.
And decide what problem the premium is solving.
For an investor entering a distant market without contractors, leasing contacts, or management infrastructure, turnkey can remove substantial execution risk.
For an investor who already has those capabilities, the same premium may be harder to justify.
Investors who want to compare purchase price, market rent, financing, and long-term returns can model those assumptions in Navikoo's analysis tools.
Turnkey works best when the buyer knows exactly which functions are being outsourced and how much that convenience costs. Once those numbers are visible, the decision becomes much easier to evaluate.